Korea's bond curve, one day: 3.47% at a year, 4.64% at thirty — then it dips
On 2026-09-04, Bank of Korea's own reference yields ran from 3.47% at one year to a peak of 4.64% at thirty years, then fell back to 4.54% at fifty. The long end of Korea's curve is not a straight climb.
AI-assisted, human-reviewed sourcing. Figures are pulled programmatically from the official sources listed at the end of this article and checked by an editor before publication.
bond-yieldgovernment-bondsktbyield-curveinterest-rateskoreabank of korea
Ask what the Korean government pays to borrow and the honest answer is a curve, not a number — and on 2026-09-04, that curve was not a straight climb. Bank of Korea’s own official reference yields ran from 3.47% at one year up to 4.64% at thirty years, the ordinary shape where longer money costs more. But at the very long end, that pattern broke: the fifty-year yield came in at 4.54% — lower than thirty.
The benchmark maturities, that day
| Maturity | Yield |
|---|---|
| 1 year | 3.469% |
| 2 years | 3.707% |
| 3 years | 3.884% |
| 5 years | 4.101% |
| 10 years | 4.360% |
| 20 years | 4.573% |
| 30 years | 4.636% |
| 50 years | 4.542% |
Every step from one year to thirty years adds yield, but the size of each step shrinks: +0.238 points crossing from one to three years, down to +0.063 points crossing from twenty to thirty. The climb is flattening well before it ends.
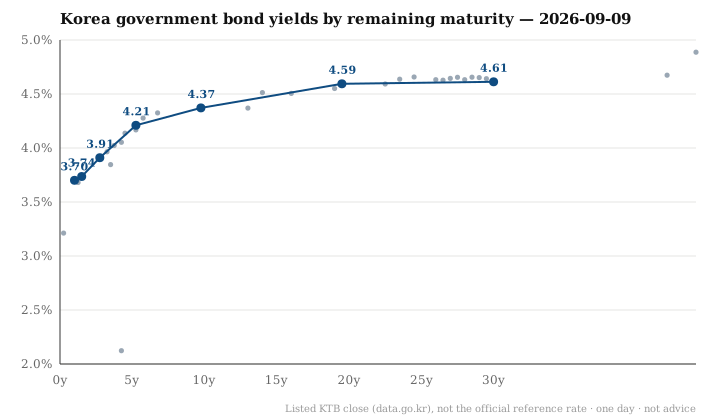
Where the curve turns over
Thirty years is the peak, not fifty. The fifty-year yield sits 0.094 points below the thirty-year yield — the one place on this curve where a longer maturity pays less than a shorter one. Every other adjacent pair, from one year up through thirty, rises with maturity; only the last segment reverses.
What this is, and is not
These are Bank of Korea’s own official benchmark reference yields for Korea Treasury Bonds, published daily by maturity — not a listed bond’s closing trade price, and not derived by matching individual bond issues to target maturities. It is also one day: a single reading of where the curve sat on 2026-09-04, not a trend and not a forecast.
We report the shape and the numbers behind it. What they mean for any decision is not ours to say — this is data, not advice.
Data & Verification Notes
- Data as of
- Sources
- Bank of Korea, ECOS (Economic Statistics System) — StatisticSearch, table 817Y002 (시장금리, market interest rates, daily), items for Korea Treasury Bond maturities 1/2/3/5/10/20/30/50 years, basis date 2026-09-04
- Cross-checks
- All eight benchmark maturities (1, 2, 3, 5, 10, 20, 30, 50 years) printed a value on the same basis date, 2026-09-04, read directly from ECOS's own daily series — no interpolation or nearest-maturity matching was needed, unlike a listed-bond scatter
- Yields rise at every step from 1 year (3.469%) to 30 years (4.636%): +0.238 points from 1y to 3y, +0.217 from 3y to 5y, +0.259 from 5y to 10y, +0.213 from 10y to 20y, +0.063 from 20y to 30y — the increase shrinks steadily as maturity lengthens
- The 50-year yield (4.542%) is lower than the 30-year yield (4.636%) by 0.094 points — the only inversion on the curve. Every other adjacent pair rises with maturity
- Excluded figures
- Any trend claim. This is one official reference-rate reading for one day, not a time series — where the curve sat on 2026-09-04, not where it is heading
- Why the 30-to-50-year segment inverts. The source gives the rate, not a reason; long-end demand and supply factors are not measured here
- This is not investment advice
The full dataset behind these figures — every listed company, every row — is available to license. SeoulMarkets data for licence →
Not investment advice. SMarkets publishes data journalism for general information only. Nothing here is investment advice, a recommendation, or an offer to buy or sell any security — any investment you make is at your own risk and responsibility. Figures are derived from official public data sources and may be revised by the issuing agency. Verify independently before acting.
Take this away — 5 cards
The figures in this article, as images. Free to repost with the address on them.